

The Paper and Paperboard Packaging Market Benefits from E-Commerce SKU Expansion, Plastic Restrictions
The Paper and Paperboard Packaging Market
The Paper and Paperboard Packaging Market Report
The Paper and Paperboard Packaging Market Analysis
The Business Research Company’s The Paper and Paperboard Packaging Global Market Report 2026 – Market Size, Trends, And Forecast 2026-2035
LONDON, GREATER LONDON, UNITED KINGDOM, October 16, 2026 /EINPresswire.com/ -- The paper and paperboard packaging sector is experiencing robust growth, largely propelled by the expanding e-commerce industry and evolving regulatory landscapes. As companies and consumers increasingly prioritize sustainability, this market is undergoing significant transformation driven by innovative materials and shifting demand patterns. Let’s explore the key market dynamics, regional insights, major players, and future prospects shaping this vital packaging segment.
Market Outlook and Growth Projections for the Paper and Paperboard Packaging Market
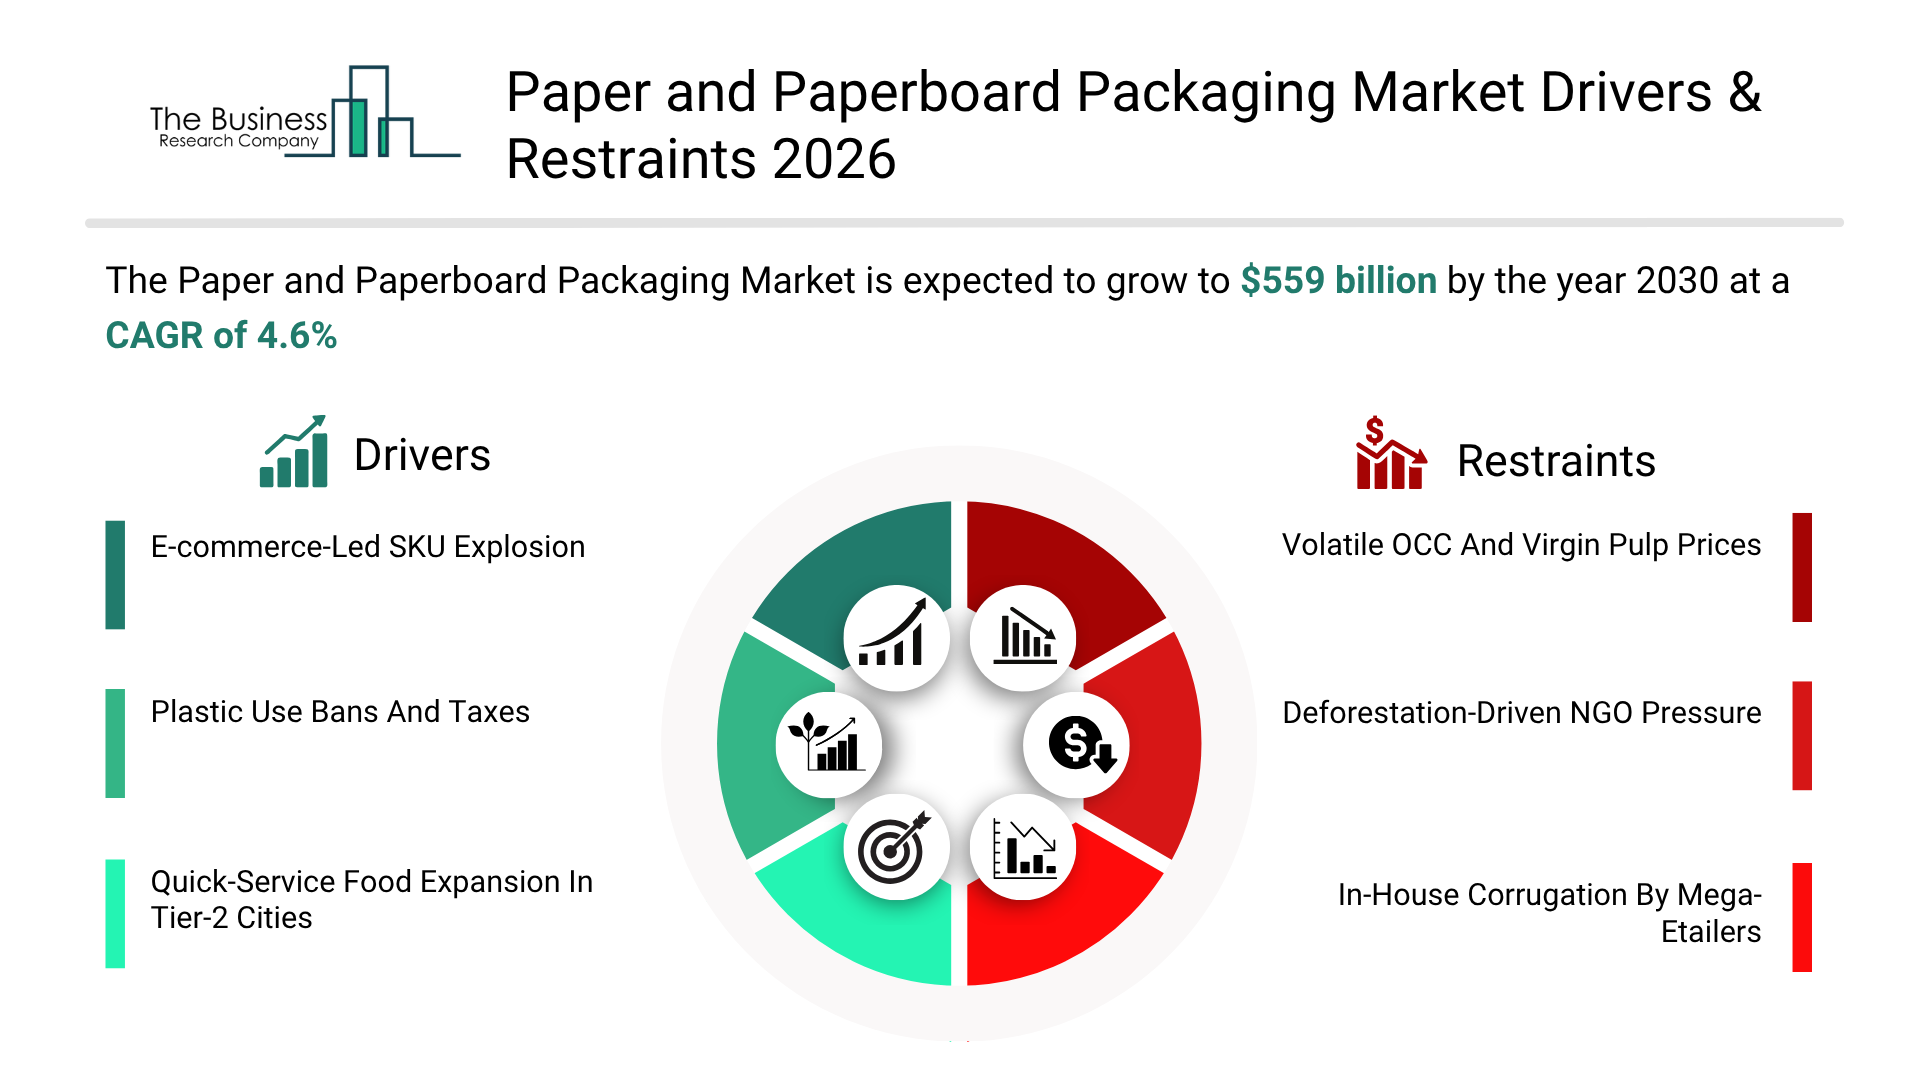
The paper and paperboard packaging market is forecast to surpass $559 billion by 2030. Positioned within the broader Paper, Plastics, Rubber, Wood and Textile industry expected to reach $10,159 billion by the same year, it will represent nearly 6% of the overall market value. Analysts anticipate a steady compound annual growth rate (CAGR) of 5% through 2030, reflecting sustained demand and innovation within the sector.
Request A Free Sample Of The Paper and Paperboard Packaging Market Report
https://thebusinessresearchcompany.com/sample_request?id=13899&type=smp&name=Paper%20and%20Paperboard%20Packaging%20Market%20Report%202026&utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Asia Pacific’s Leading Role in the Paper and Paperboard Packaging Market
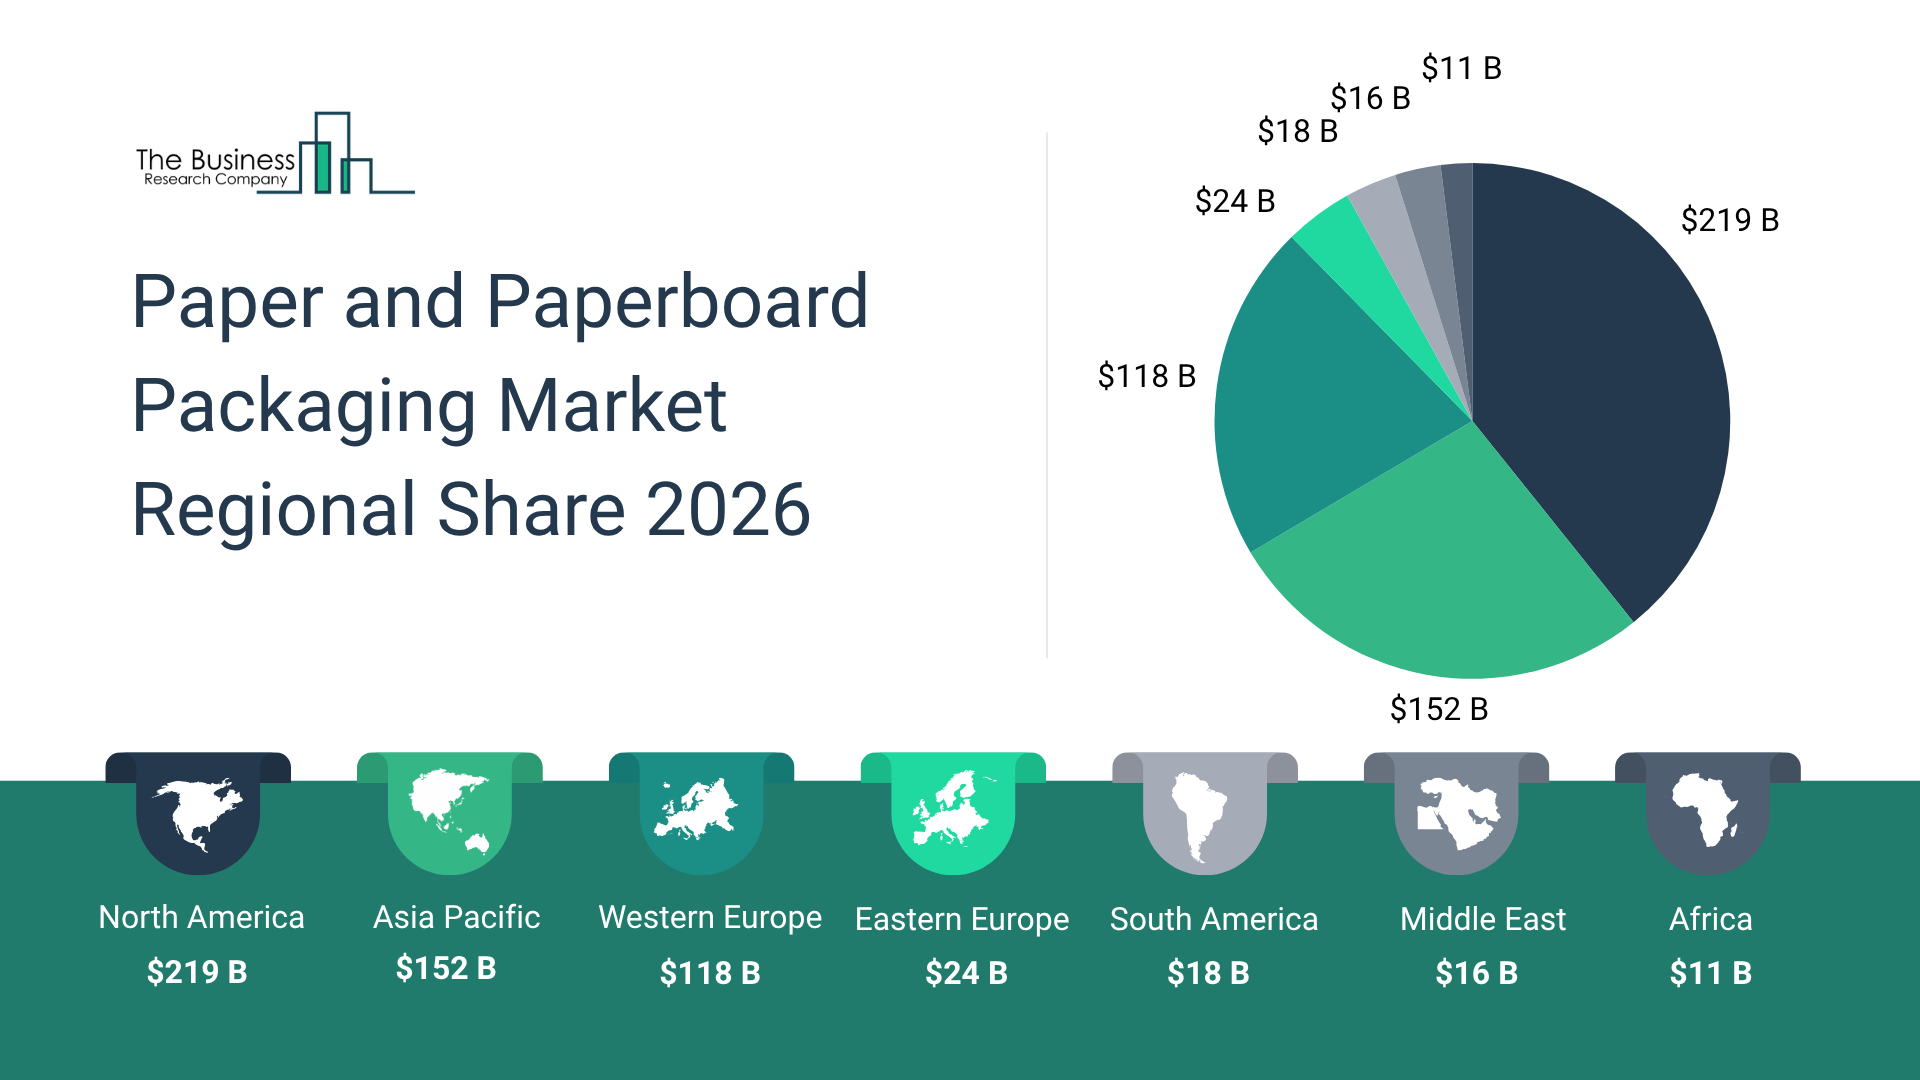
Asia Pacific is set to dominate the paper and paperboard packaging landscape in 2030, with a market value reaching $219 billion, rising from $168 billion in 2025. This reflects a healthy CAGR of 6%, driven by factors such as growing food processing industries, increasing packaged consumer goods consumption, rapid urbanization, and the rise of organized retail and e-commerce. Additionally, governmental initiatives supporting recyclable and renewable packaging materials are fueling expansion throughout emerging economies in the region.
The United States as a Major Market Player in Paper and Paperboard Packaging
The USA is projected to be the largest single-country market for paper and paperboard packaging by 2030, valued at $126 billion compared to $106 billion in 2025, growing at a CAGR of 4%. This growth stems from a mature packaging industry, rising demand for convenience and ready-to-eat foods, increased adoption of premium paperboard in consumer goods and healthcare, and a well-established recycling infrastructure that encourages circular economy principles. Furthermore, innovation in lightweight, high-performance materials and customized packaging formats support brand differentiation across sectors.
Access The Detailed Paper and Paperboard Packaging Market Report Here
https://thebusinessresearchcompany.com/report/paper-and-paperboard-packaging-global-market-report?utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Primary Drivers Behind the Paper and Paperboard Packaging Market Expansion
One major driver fueling growth is the proliferation of SKUs driven by e-commerce. Online retailers are expanding their product offerings, creating demand for versatile and personalized packaging solutions. Paper and paperboard materials provide excellent printability, protection, and handling efficiency, making them ideal for a wide variety of SKUs distributed through omnichannel networks. This factor is expected to contribute roughly 2.0% annual growth to the market.
Another key influence is the increasing implementation of bans and taxes on plastic usage. Governments worldwide are restricting single-use plastics and encouraging greener alternatives. Paper-based packaging, being recyclable and renewable, is widely accepted by consumers and businesses alike, pushing companies to accelerate their transition to fiber-based formats to meet sustainability and regulatory requirements. This driver is projected to add about 1.9% yearly growth to the market.
Growth Opportunities from Quick-Service Food Expansion in Emerging Urban Centers
The rapid expansion of quick-service food outlets in tier-2 cities is also supporting market growth. Rising disposable incomes and shifting lifestyles in developing urban areas are boosting demand for convenient dining options, which in turn increases the need for paperboard containers, cartons, wraps, and takeaway packaging. These products offer convenience, effective branding, and food safety, prompting suppliers to increase capacity and develop specialized foodservice packaging. This segment is expected to contribute around 1.5% annual growth.
Product Segments Adding Significant Value to the Paper and Paperboard Packaging Market
Folding cartons, corrugated boxes, and other product types are the primary contributors to market value, forecasted to add over $112 billion between 2025 and 2030. Folding cartons are projected to grow by $54 billion, corrugated boxes by $43 billion, and other product types by $15 billion. This surge is driven by increasing demand for premium packaging in consumer goods, higher volumes through retail and digital commerce, broader adoption of sustainable fiber-based materials, and innovations in lightweight, durable, and visually appealing packaging that protect products and enhance shelf presence.
Folding Cartons as a Dominant Product Segment in Paper and Paperboard Packaging
Among product categories, folding cartons are expected to constitute the largest segment in 2030, accounting for 48% or $268 billion of total sales. Their popularity is due to their attractive and printable nature, growing consumption in food, pharmaceuticals, and personal care sectors, preference for lightweight and cost-effective packaging, strong branding impact, increasing recyclability, and continuous improvements in carton design and manufacturing technology.
Segmentation of the Paper and Paperboard Packaging Market
The market is further divided by grade into categories such as solid bleached sulfate, coated unbleached kraft paperboard, folding boxboard, white lined chipboard, glassine and greaseproof paper, label paper, and others. By end-user industry, the segmentation encompasses food, beverage, healthcare, personal care, electrical, and additional sectors.
Rising Adoption of Lightweight Paperboard Packaging Solutions
Lightweight paperboard packaging is gaining traction by enhancing material efficiency, reducing resource consumption, and improving sustainability. For instance, in March 2026, Clearwater Paper Corporation introduced Velora, a lightweight folding carton paperboard designed for foodservice and consumer packaging. This product offers optimized fiber blends for superior converting performance and yield with less material, while meeting sustainability certifications such as SFI fiber sourcing and FDA 21 CFR compliance.
Market Structure and Competitive Landscape of Paper and Paperboard Packaging
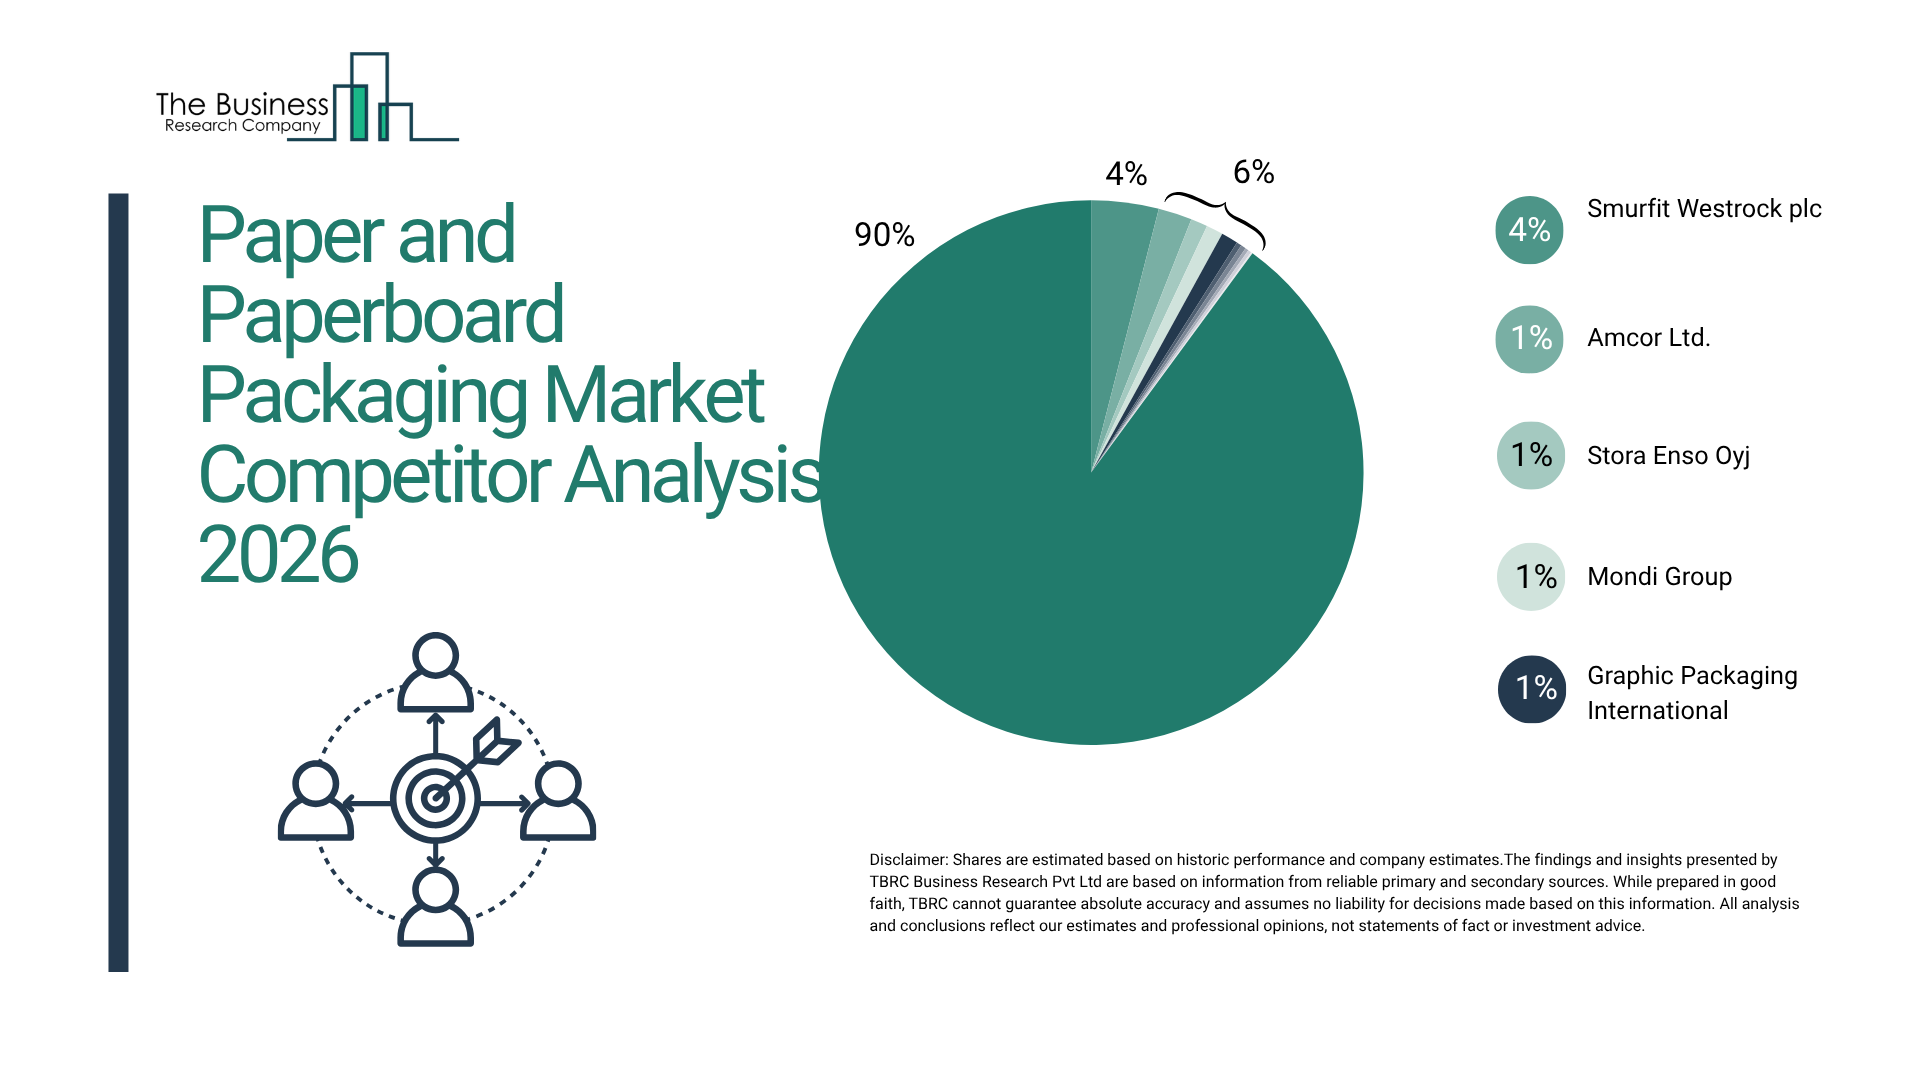
The paper and paperboard packaging industry remains fragmented, with the top 10 companies holding only 10% of total revenue in 2024. Moderate entry barriers stem from sustainability regulations, recycling standards, capital requirements, and the need for large-scale manufacturing and distribution networks. Leading firms sustain their positions through diverse product portfolios, strong global supply chains, established relationships with FMCG and e-commerce customers, and continuous innovation focused on recyclable materials, lightweight solutions, and high-barrier coatings aligned with environmental compliance and circular economy goals.
Leading Companies Dominating Market Revenue Shares
The top market leaders by 2024 revenue include Smurfit Westrock plc with a 4% share, Amcor Ltd. at 2%, followed by Stora Enso Oyj, Mondi Group, Graphic Packaging International, and others holding between 0.1% and 1%. These companies compete by advancing sustainable packaging technologies, improving barrier coatings for product protection, expanding production capacity to enhance supply reliability, and incorporating smart packaging features for improved traceability and quality control.
Smurfit Westrock plc’s Market Leadership Position
Smurfit Westrock plc emerged as the leading company in paper and paperboard packaging sales in 2024, holding a 4% market share. Its packaging division offers a broad array of corrugated packaging, containerboard, paperboard solutions, and sustainable products serving the food and beverage, retail, e-commerce, and industrial sectors worldwide.
Key Industry Players Shaping the Paper and Paperboard Packaging Market
Besides Smurfit Westrock plc and Amcor Ltd., notable companies include Stora Enso Oyj, Mondi Group, Graphic Packaging International, Oji Holdings Corporation, International Paper Company, Sonoco Products Company, UPM-Kymmene Corporation, Packaging Corporation of America, Metsä Group, Nippon Paper Industries Co. Ltd, Billerud AB, Mayr-Melnhof Karton AG, Rengo Co., Ltd, Svenska Cellulosa Aktiebolaget SCA, Cascades Inc., Domtar Corporation, Visy Industries Australia Pty Ltd, South Africa Pulp and Paper Industries Ltd (Sappi), and Shandong Bohui Paper Company Ltd.
Overview of the Paper and Paperboard Packaging Value Chain
The raw material supply side features companies such as International Paper Company, WestRock Company, Packaging Corporation of America, Smurfit Kappa Group plc, Stora Enso Oyj, UPM-Kymmene Corporation, Mondi plc, Sappi Limited, Nine Dragons Paper Holdings Limited, Oji Holdings Corporation, Nippon Paper Industries Co. Ltd., Sonoco Products Company, DS Smith plc, Georgia-Pacific LLC, Domtar Corporation, Canfor Corporation, Clearwater Paper Corporation, Metsä Board Corporation, Burgo Group S.p.A., Lecta Group, Asia Pulp and Paper Group, Asia Symbol Corporation, Heinzel Group, Resolute Forest Products Inc., and Double A Public Company Limited.
Wholesalers and distributors active in this market include Antalis International, Veritiv Corporation, Japan Pulp and Paper Company Limited, Central National-Gottesman Inc., Imperial Dade, BradyPLUS Distribution, Kelly Spicers Inc., Bunzl plc Packaging Division, Inapa Group, Rajapack Group, Macfarlane Group plc, All Packaging Company, Berlin Packaging LLC, TricorBraun Inc., O.Berk Company LLC, C.L. Smith Company, Packaging Corporation International, The Cary Company, SupplyOne Inc., Uline Inc., Shorr Packaging Corporation, Associated Packaging Inc., IPS Packaging & Automation, Complete Packaging Products Inc., and Atlantic Packaging.
Major End Users Driving Demand in Paper and Paperboard Packaging
Leading end users include Amazon.com Inc., Walmart Inc., Costco Wholesale Corporation, The Procter and Gamble Company, Nestlé S.A., Unilever plc, PepsiCo Inc., The Coca-Cola Company, Mondelez International Inc., McDonald’s Corporation, Starbucks Corporation, Tesco plc, Carrefour S.A., Target Corporation, Aldi Einkauf GmbH & Co. oHG, Lidl Stiftung & Co. KG, IKEA Group, Domino’s Pizza Inc., Yum Brands Inc., Colgate Palmolive Company, Johnson and Johnson, L’Oréal S.A., Kellogg Company, Kraft Heinz Company, and Danone S.A.
New analytical features added to our 2026 market reports:
• Market attractiveness scoring and analysis
• Total addressable market (TAM) analysis
• Company scoring matrix graphics and tables
• Excel-based forecasting dashboards
• Market hotspots infographics
• Key technologies and future trend analysis
• Updated graphics and tables
Learn More About The Business Research Company
The Business Research Company (www.thebusinessresearchcompany.com) is a leading market intelligence firm renowned for its expertise in company, market, and consumer research. We have published over 30,000+ reports across 27 industries and 60+ geographies. Our research is powered by 1,500,000 datasets, extensive secondary research, and exclusive insights from interviews with industry leaders.
We provide continuous and custom research services, offering a range of specialized packages tailored to your needs, including Market Entry Research Package, Competitor Tracking Package, Supplier & Distributor Package and much more.
Disclaimer: Please note that the findings, conclusions and recommendations that TBRC Business Research Pvt Ltd delivers are based on information gathered in good faith from both primary and secondary sources, whose accuracy we are not always in a position to guarantee. As such TBRC Business Research Pvt Ltd can accept no liability whatever for actions taken based on any information that may subsequently prove to be incorrect. Analysis and findings included in TBRC reports and presentations are our estimates, opinions and are not intended as statements of fact or investment guidance.
Contact Us:
The Business Research Company
Americas +1 310-496-7795
Europe +44 7882 955267
Asia & Others +44 7882 955267 & +91 8897263534
Email: marketing@tbrc.info
Follow Us On:
LinkedIn: https://in.linkedin.com/company/the-business-research-company
Oliver Guirdham
The Business Research Company
+44 7882 955267
info@tbrc.info
Visit us on social media:
LinkedIn
Facebook
X
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
